

Popular Categories

Politics

Geo Economics

Lifestyle

Analysis

Geopolitics
Civilizational Lens
Defence

China’s Infrastructure Boom Hits Its Limit as Debt Mounts and Transport Investment Declines
5 Nov 2026
Created by
The BV Team
For over thirty years China constructed its dominance with an exceptional growth of road, rail, bridge and port networks, and industrial corridors. That infrastructure helped make the country the manufacturing world power house, cut logistics costs and linked previously isolated provinces to the international market. But the economic system that was key to modern China is starting to feel the strain. Beijing is posing a hard question: How much more do you need when the revenue from the infrastructure is becoming even more unknown?
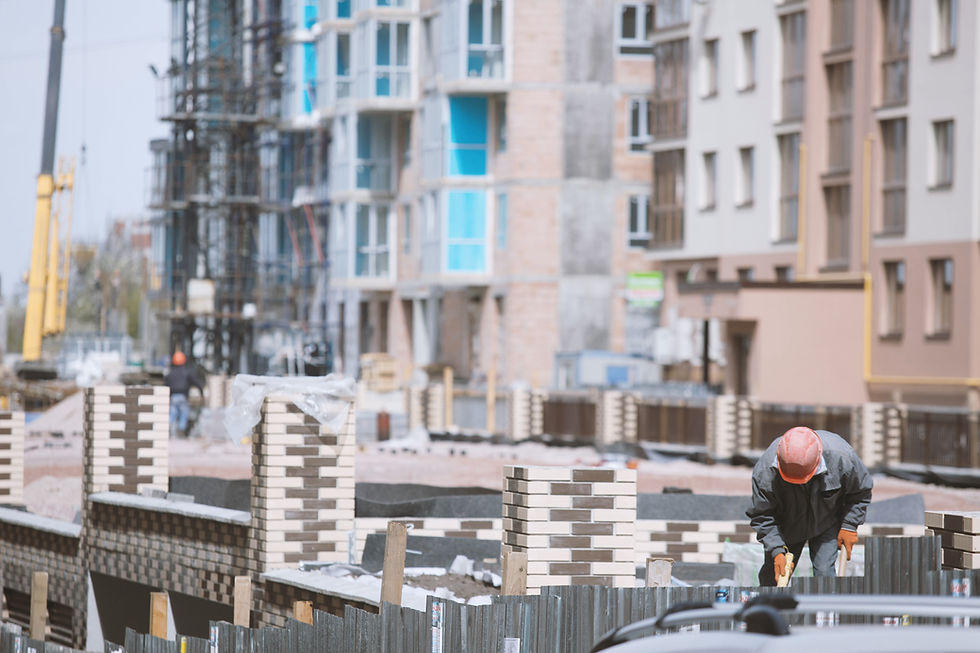
The latest official data shows the extent of the problem. Fixed-investment spending fell 7.2% in the first nine months of 2026, with a total fixed investment of RMB 33.41 trillion, or USD 4.7 trillion, reported by China's National Bureau of Statistics. The investment in infrastructure decreased by 4.2%, and road transportation investment decreased by 9.9%. Worse was the 10.4% drop in non-governmental investment, indicating private investors are not keen on investing in the next generation of China's economic growth.
These are not just a few temporary lulls in the building sector. They represent a shift in a business-oriented economy that has always been built on investment to make up for tepid household spending and in which local governments have relied heavily on construction to provide jobs, economic output, and political credibility.
The transport infrastructure in China is still a marvel. It is the world's largest high speed railway network with over 48 000 kilometres of track. It has an expressway network of some 190,000 km and its ports account for the majority of the world's container-handling facilities. The investments enabled the efficient transport of products by Chinese manufacturers from industrial centres to international shipping terminals, and strengthened the country's competitive position.
But at that point, the economics of the infrastructure transformation has been done by the route that makes the most sense for business. The railway line from Beijing to Shanghai has the potential to draw a significant number of passengers and goods. Such a costly link between low-density western cities might provide strategic and social advantages without producing enough income to offset the cost and financing of the project.
The nation has continued to expand its railway system. China State Railway Group invested 601.2 billion yuan in the first 9 months of 2026, which represented an increase of 1.3%, while 1,625 kilometres of new railway lines were opened. Beijing's continued spending on the railways, but not on the roads, indicates that it is not giving up on infrastructure, but rather being more selective.
However, the selection process does not eliminate any liabilities incurred in previous construction cycles. The operating and investment costs of high-speed rail projects are high, such as the maintenance cost, electric power consumption, signalling system, rolling stock and debt service. If passenger numbers are not as expected from commercial operations, then operating revenues may not be enough to meet the total cost.
The issue also affects China's local-government financing system. Local authorities financed vehicles, land-related revenues, and borrowed to fund construction for years. The extended property downturn has made it harder on land-sale revenue and has left the financial resources of landowners increasingly strained to meet their existing obligations, or to fund further projects.
This results in a vicious circle that may be harmful. When government currencies are under pressure, governments cut construction spending, contractors are given less work, industrial demand and employment suffer, and as economies slow, government revenues suffer as well.
The impact is considerably more than an issue for construction companies—particularly for businesses. Infrastructure spending puts cement producers, steel makers, heavy-equipment suppliers, engineering companies and regional banks at risk. Declining new projects could lead to further pressure on excess capacity in construction-related sectors and push Chinese manufacturers to look for new export markets.
The Chinese have already vast experience in railway building, tunnelling, bridge building, port development and heavy machinery. When domestic demand slows, going abroad with the ability to sell these skills becomes more alluring. Southeast Asia, Africa, Central Asia and Middle East may be vital markets for Chinese construction firms to replace their revenues.
But the Belt and Road initiative has its own monetary limitations. Some of the countries taking part in the project are facing sovereign debt problems, devaluation of their currencies, and the debt service burdens of previous infrastructure investments. This therefore creates a more complex situation for Chinese lenders than in the early stages of the expansion of the initiative.
These developments should be looked at with caution by India. The slowdown in China's infrastructure may present opportunities for Indian steelmaking companies, engineering firms and construction-equipment makers, including when foreign customers look for alternatives to Chinese suppliers. Meanwhile, if the Chinese exports come in at competitive prices, Indian manufacturers might face stiff competition.
This comparison of the two Asian economies is especially illuminating. China is facing the drawback of a vast network of infrastructure that has already linked most of the key commercial hubs. By contrast, India has significant gaps in freight efficiency, railway capacity as well as urban transport and industrial connectivity.
This disparity offers a chance as well as a warning. The infrastructure investments in India need to be judged in terms of freight demand, productivity of industries, employment creation and the long-term financial viability. However, it is important to build assets without economic activity to back them up, or it could be a recipe for repeating the financial challenges that are currently faced by the Chinese provincial governments.
The real challenge for Beijing is to shift from investment-oriented growth to greater domestic consumption, boosting household incomes and productivity. Improvement of infrastructure can help to increase economic efficiency but it cannot replace the demand of the consumers or investment in the private sector, which is profitable.
There is no absolute limit to the transport investment in China. Funding will be continued for strategic railway corridors, logistics upgrades and technologically advanced transport systems. The end of a false belief has come at the end of the road: that every kilometre of new highway or railway brings some real economic gain.